
The invisible architecture behind every tokenized Treasury bill, real estate deed, and private credit loan.
Why This Article Exists
You've seen the headlines: BlackRock's BUIDL hits $500M AUM. Ondo's OUSG yields 5.2% on-chain. Figure originates $1B+ in HELOCs on Provenance. Securitize tokenizes Hamilton Lane funds.
Under the hood, every single one relies on the same invisible component: a legal wrapper.
Not a smart contract. Not an oracle. Not a bridge.
A legal wrapper — a Cayman SPV, a Delaware Statutory Trust, a Series LLC, a Luxembourg SICAV — is the legal entity that actually owns the real-world asset. Your token? It's just a digital claim on that entity.
Choose the wrong wrapper, and you get: tax leakage, regulatory enforcement, or — worst case — token holders becoming unsecured creditors in bankruptcy court.
This article is your decision framework. No vendor pitch. No jargon without definition. Just the structural logic you need to pick the right wrapper for your asset, your investors, and your jurisdiction.
What Is a Legal Wrapper? (The 4-Layer Stack)
Most explanations stop at "an SPV holds the asset." That's Layer 1 of 4.
A production-grade legal wrapper is a stack of four independent but interlocking layers. Miss one, and the structure leaks.
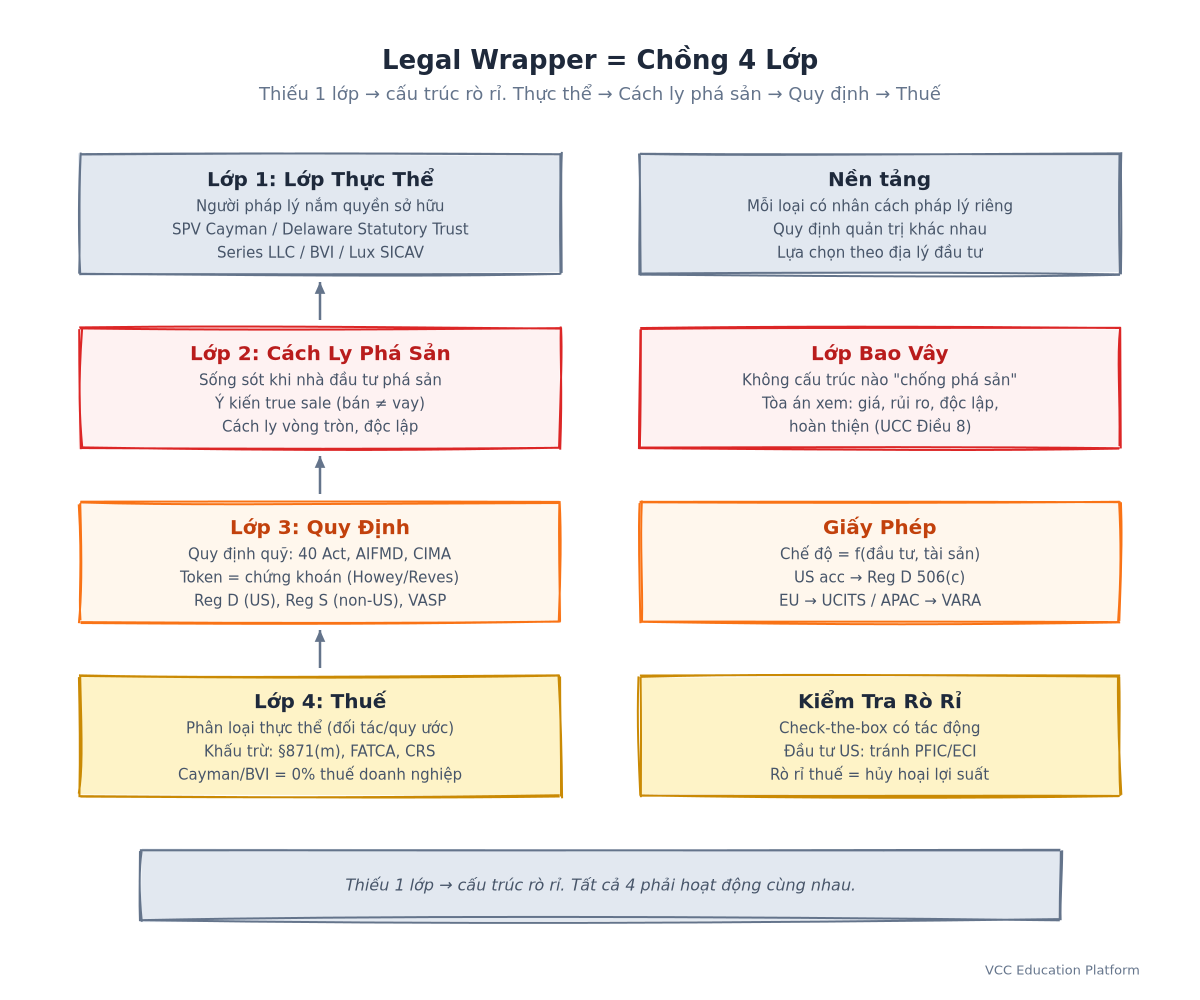
Layer 1: Entity Layer — The Legal Person
The corporate vehicle that holds legal title. Options:- Cayman SPV (Exempted Company or Segregated Portfolio Company)
- Delaware Statutory Trust (DST)
- Series LLC (Delaware)
- BVI Business Company
- Luxembourg SICAV (Société d'Investissement à Capital Variable)
Each has distinct legal personality, capacity, and governance rules.
Layer 2: Bankruptcy Remoteness Layer — The Fortress
This is why you don't just use a regular LLC. The wrapper must survive the originator's bankruptcy.- True sale opinion: Courts must treat asset transfer as a sale, not a secured loan
- Ring-fencing: SPV assets segregated from originator's creditors
- Independent trustee/directors: No control by originator
- Non-petition covenants: SPV cannot voluntarily file bankruptcy
Critical insight: No structure is "bankruptcy-proof." The question is remoteness — how many legal hurdles between originator failure and asset seizure.
Layer 3: Regulatory Layer — The License
What regime governs the wrapper?- Fund regulation: SEC '40 Act, AIFMD (EU), CIMA (Cayman), SFC (HK)
- Securities law: Token = security (Howey/Reves) → Reg D (US), Reg S (non-US), prospectus (retail)
- VASP/ASP licensing: Cayman VASP Act, EU MiCA, Singapore VARA, HK SFC
- AML/KYC: Travel Rule, FATF compliance, on-chain analytics (Chainalysis, Elliptic)
Layer 4: Tax Layer — The Leak Check
- Entity classification: Partnership vs corporation vs trust (check-the-box elections)
- Withholding tax: US §871(m), FATCA, CRS, treaty benefits
- Investor-level tax: PFIC rules, CFC rules, effectively connected income (ECI)
- Jurisdiction neutrality: Cayman/BVI = no corporate tax; Delaware = state franchise tax only
Vietnam context: VN investors accessing Cayman SPVs (OUSG, BUIDL) face Circular 111/2013/TT-BTC offshore investment reporting. No domestic legal wrapper recognition yet under Decree 13/2023 — Singapore VARA-licensed SPV is the current workaround.
The Decision Tree: Investor Geography First
Don't compare features. Start with who holds the tokens.
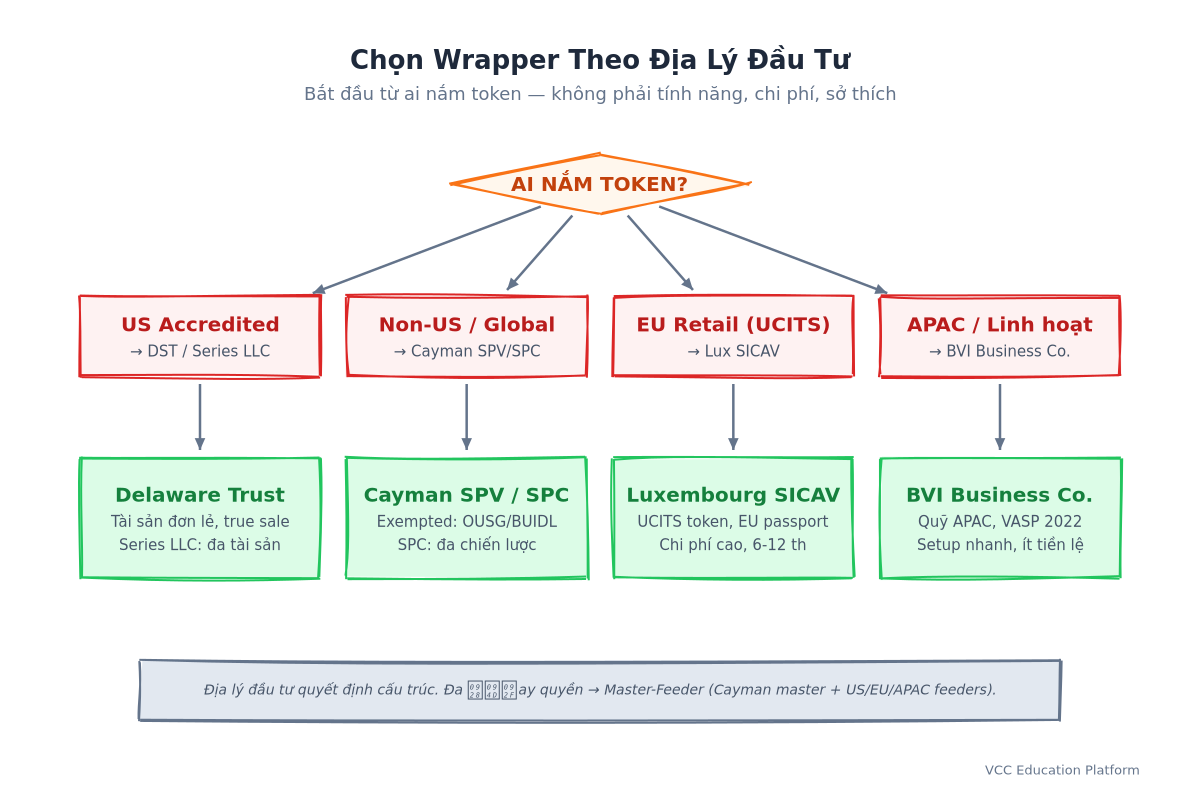
Path A: US Accredited Investors Only → Delaware Statutory Trust or Series LLC
Why: US securities law (Reg D 506(c)) + US tax simplicity + bankruptcy remoteness precedent.
| Structure | Best For | Key Advantage | Key Risk |
|---|---|---|---|
| Delaware Statutory Trust | Single-asset, US-facing (HELOCs, Treasuries, private credit) | True sale precedent; trustee independence; UCC Article 8 "security" treatment | No series segregation; trustee fees |
| Series LLC | Multi-asset platforms (Securitize model) | Single entity admin; each series = separate liability | Bankruptcy isolation untested in some courts |
Real example: Figure uses DST for HELOC securitization on Provenance. WisdomTree Prime uses DST for tokenized money market fund. Securitize uses Series LLC for Hamilton Lane / KKR fund tokenization.
Path B: Non-US / Global Institutional → Cayman SPV (Exempted Company or SPC)
Why: Tax neutrality, CIMA regulatory flexibility, global investor familiarity, SPC for multi-asset.
| Structure | Best For | Key Advantage | Key Risk |
|---|---|---|---|
| Cayman Exempted Co. | Single large fund (OUSG, BUIDL feeder) | Simple, fast, well-understood | One asset pool = cross-contamination risk |
| Cayman SPC (Segregated Portfolio Company) | Multi-strategy platforms | Statutory ring-fencing per portfolio | Slightly higher setup cost |
Real example: Ondo OUSG = Cayman Exempted Company holding US Treasuries. BlackRock BUIDL = Master-feeder with Cayman feeder. Franklin Templeton BENJI = Cayman SPV. Mountain Protocol USDM = Cayman SPV.
Path C: EU Retail Access (UCITS) → Luxembourg SICAV
Why: UCITS passport = 27 EU markets. Retail-eligible. CSSF supervision.
| Structure | Best For | Key Advantage | Key Risk |
|---|---|---|---|
| Luxembourg SICAV | Tokenized UCITS funds | EU passport; retail distribution; established admin ecosystem | Highest cost ($100k+ setup); 6-12 month authorization |
Real example: FundRock / Tokeny tokenized SICAV structures. DWS / Deutsche Bank exploring SICAV tokenization.
Path D: Asia-Pacific / Flexible → BVI Business Company
Why: BVI VASP Act 2022, no capital gains tax, fast incorporation (24-48hrs), common for Asian family offices.
| Structure | Best For | Key Advantage | Key Risk |
|---|---|---|---|
| BVI Business Co. | APAC-focused funds, tokenized private credit | Speed; cost; VASP sandbox | Less precedent for bankruptcy remoteness vs Cayman |
Real example: Multiple Asian private credit tokenization platforms use BVI SPVs.
Path E: Multi-Jurisdiction → Master-Feeder
Why: One master fund, multiple feeders for different investor bases.
` Master Fund (Cayman SPC) ├── US Feeder (Delaware LP/LLC) → Reg D investors ├── EU Feeder (Lux SICAV/FCP) → UCITS/retail └── APAC Feeder (BVI/Singapore) → VARA/MAS investors `
Real example: BlackRock BUIDL uses master-feeder. Securitize structures often use this for global distribution.
Deep Dive: The Big Three Structures
1. Cayman SPV — The Global Standard
Legal form: Exempted Company (single asset) or Segregated Portfolio Company (multi-asset) Governance: Independent directors (min 2), Cayman-licensed administrator Bankruptcy remoteness: Strong — Cayman courts respect ring-fencing; SPC has statutory segregation Regulatory: CIMA registration (light for closed-ended); VASP license if tokens issued Tax: Zero corporate tax; no withholding on dividends/interest Timeline: 4-6 weeks Cost: $25k-$50k setup + $15k-$30k/yr admin
Why it wins: Investor familiarity. Every institutional LP knows Cayman. Every fund admin operates there. Every lawyer has the precedents.
The catch: US investors need a blocker (Delaware LP/LLC) to avoid ECI/PFIC issues. Adds layer, cost, complexity.
2. Delaware Statutory Trust — The US Native
Legal form: Statutory trust under 12 Del. C. § 3801 et seq. Governance: Trustee (institutional, e.g., CSC, Wilmington Trust) + beneficial owners Bankruptcy remoteness: Gold standard — Delaware courts have 30+ years of true sale precedent (asset-backed securitization). Trustee independence is statutory. Regulatory: No fund registration if private placement (Reg D); '40 Act if retail Tax: Pass-through (grantor trust) or partnership; no Delaware income tax for non-residents Timeline: 3-5 weeks Cost: $15k-$30k setup + $10k-$20k/yr trustee fees
Why it wins: True sale opinions are routine. UCC Article 8 treats beneficial interests as "securities" — perfect for token mapping. US investors get clean tax treatment.
The catch: No series segregation. One trust = one asset pool. Multi-asset needs multiple DSTs or a master trust structure. Non-US investors may face withholding tax complexity.
3. Series LLC — The Platform Play
Legal form: Delaware LLC with series under 6 Del. C. § 18-215 Governance: Single manager/LLC agreement governs all series Bankruptcy remoteness: Statutory but untested — Delaware law says each series' assets are separate, but no federal bankruptcy court has ruled on series isolation in Chapter 11. Some scholars warn of "substantive consolidation" risk. Regulatory: Each series can be separate "fund" for '40 Act purposes Tax: Each series = separate partnership (check-the-box); single EIN possible Timeline: 2-4 weeks (fastest) Cost: $10k-$20k setup (single entity) + $5k-$15k/yr admin
Why it wins: Operational efficiency. One entity, one bank account, one admin, infinite series. Securitize uses this to onboard funds in days, not weeks.
The catch: Bankruptcy uncertainty. If the platform fails, do all series get pulled in? No court has said "no." For high-value institutional assets, this is a blocker.
Comparison Matrix: At a Glance
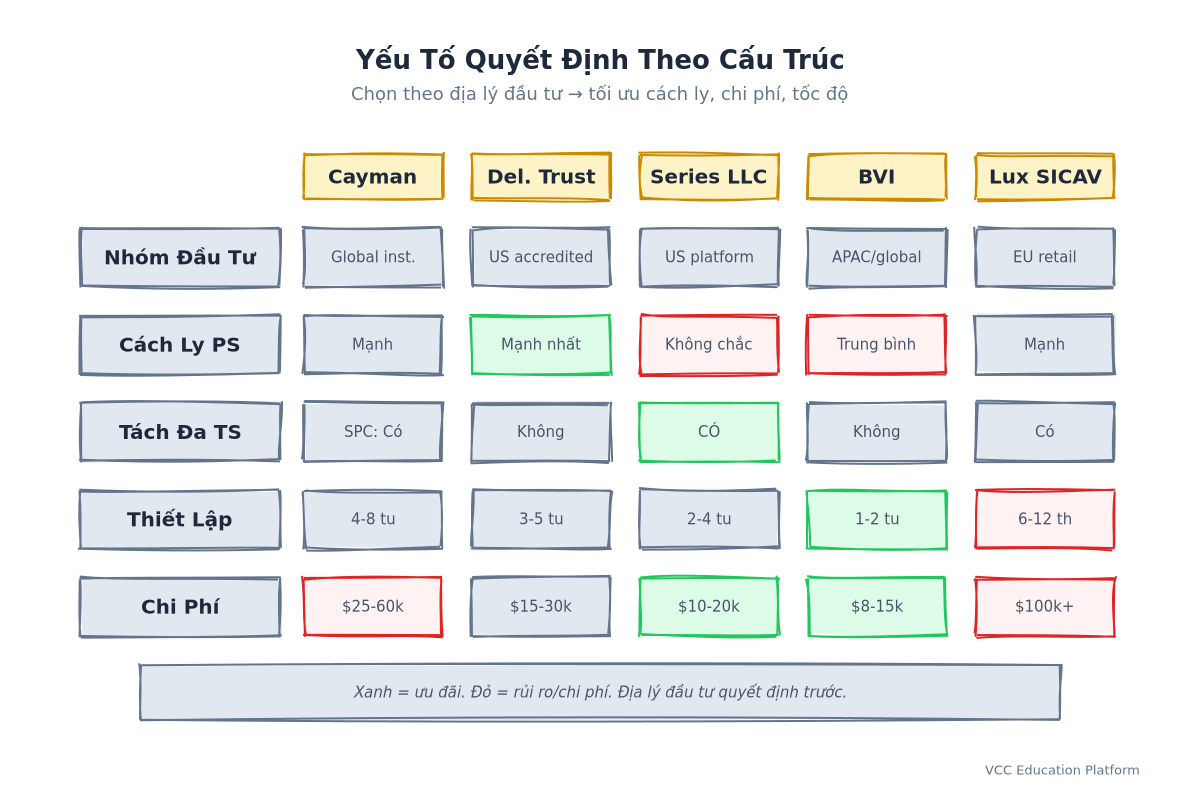
| Dimension | Cayman SPV (Exempted) | Cayman SPC | Delaware Statutory Trust | Series LLC | BVI Bus. Co. | Lux SICAV |
|---|---|---|---|---|---|---|
| Primary Investor Base | Global inst. | Global inst. multi-asset | US accredited | US accredited platform | APAC/global | EU retail + inst. |
| Bankruptcy Remoteness | Strong | Strongest (statutory) | Strongest (precedent) | Uncertain (untested) | Moderate | Strong (EU insolvency law) |
| Multi-Asset Segregation | No (separate SPVs) | Yes (statutory) | No (separate DSTs) | Yes (statutory) | No (separate cos) | Yes (sub-funds) |
| Setup Time | 4-6 wks | 6-8 wks | 3-5 wks | 2-4 wks | 1-2 wks | 6-12 mos |
| Setup Cost | $25-50k | $35-60k | $15-30k | $10-20k | $8-15k | $100k+ |
| Annual Admin | $15-30k | $25-40k | $10-20k | $5-15k | $10-20k | $50k+ |
| Tax Neutrality | Full | Full | US pass-through | US pass-through | Full | EU (UCITS) |
| Regulatory Burden | Low (closed-end) | Medium | Low (private) | Low (private) | Low-Medium | High (UCITS) |
| Investor Familiarity | Highest | High | High (US) | Medium | High (APAC) | High (EU) |
| Token Mapping | Share/Note | Share/Note per portfolio | Beneficial interest | Series interest | Share | Share/Unit |
The Bankruptcy Remoteness Deep Dive (The Part Everyone Skips)
This is where token holders lose money. Read carefully.
True Sale vs. Secured Lending
When Originator transfers assets to SPV, two legal characterizations exist:
| Characterization | Token Holder Rights | Recovery in Originator Bankruptcy |
|---|---|---|
| True Sale | Own SPV shares/notes → own pro-rata asset claim | Assets safe in SPV. Originator creditors cannot reach them. |
| Secured Loan | Originator still owns assets; SPV has lien | Assets in Originator estate. Token holders = secured creditors (better than unsecured, but delayed, haircut risk). |
Courts look for:
- Purchase price paid (not nominal)
- Risk transfer (SPV bears economic risk)
- No recourse to Originator
- Independent decision-making (SPV directors/trustee not controlled by Originator)
- Perfection (UCC Article 9 filing for non-securities; Article 8 control for securities)
The UCC Article 8 vs Article 9 Trap
Tokens are "securities" under UCC Article 8 (investment contract = security = "security entitlement").
- Control (not filing) perfects security interest
- Control = token in SPV's wallet, SPV has exclusive control
- Much cleaner than Article 9 filing
But: If court recharacterizes token as not a security → Article 9 applies → filing required → perfection gaps possible.
Figure's innovation: Provenance blockchain is the control system. Token in SPV wallet = control perfected on-chain. This is why Figure uses DST + Provenance — the blockchain is the perfection mechanism.
The Untested Question
If a Delaware Statutory Trust holding tokenized Treasuries fails bankruptcy remoteness, are token holders unsecured creditors?
No court has ruled. The true sale opinion from counsel is a prediction, not a guarantee. Every wrapper structure carries this tail risk.
Mitigation:
- Multiple legal opinions (originator + SPV counsel)
- Rating agency review (KBRA, DBRS Morningstar on OUSG/BUIDL)
- On-chain proof of reserve (Chainlink PoR) — proves assets exist now, not just at issuance
Cost & Timeline Reality Check
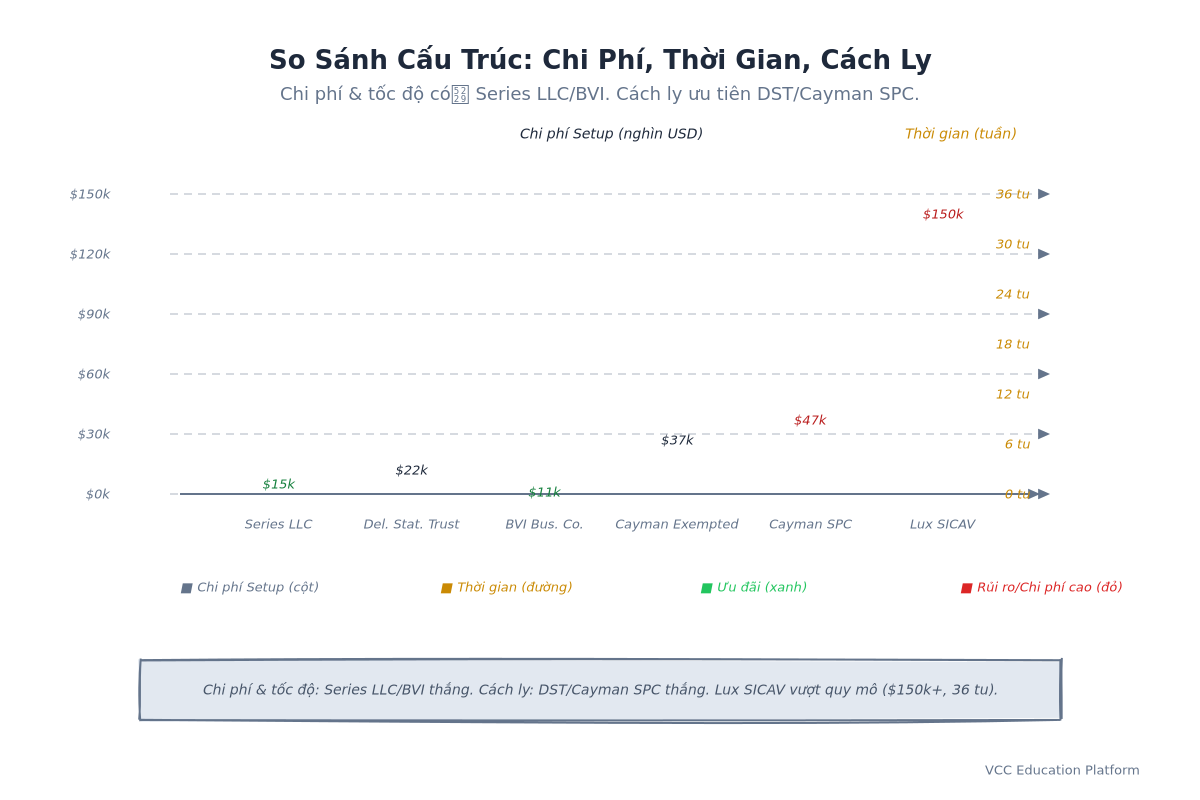
| Structure | Setup Cost | Annual Cost | Timeline | Best For |
|---|---|---|---|---|
| Series LLC | $10k-$20k | $5k-$15k | 2-4 weeks | Platforms, multi-asset, speed |
| Delaware Statutory Trust | $15k-$30k | $10k-$20k | 3-5 weeks | US-facing, single asset |
| BVI Business Company | $8k-$15k | $10k-$20k | 1-2 weeks | Speed, APAC, cost-sensitive |
| Cayman Exempted Co. | $25k-$50k | $15k-$30k | 4-6 weeks | Global institutional, single asset |
| Cayman SPC | $35k-$60k | $25k-$40k | 6-8 weeks | Multi-asset institutional |
| Luxembourg SICAV | $100k+ | $50k+ | 6-12 months | EU retail, UCITS passport |
Hidden costs not in above:
- Legal opinions (true sale, tax, regulatory): $25k-$100k+
- Audit (annual): $15k-$50k
- Fund administrator: $20k-$100k/yr
- Custody (Fireblocks, Copper, Anchorage): $10k-$50k/yr
- Oracle/PoR (Chainlink): $10k-$100k/yr
- Compliance/KYC/AML stack: $20k-$100k/yr
Total first-year all-in: $150k-$500k+ depending on structure and service providers.
How the Major Protocols Chose (Case Studies)
Ondo Finance (OUSG, USDY) → Cayman Exempted Company
- Why: Non-US investors (Reg S), US Treasury collateral, global distribution
- Structure: Cayman SPV holds Treasuries → issues tokens to non-US persons
- US version (OUSG): Separate Cayman feeder → US master fund (Delaware LP) for Reg D investors
- Key insight: Master-feeder lets them serve both markets from one asset pool
BlackRock BUIDL → Master-Feeder (Cayman + Delaware)
- Why: Largest asset manager; needs US + non-US + potential EU retail later
- Structure: Master fund (Cayman) → US feeder (Delaware LP) + non-US feeder (Cayman)
- Key insight: BlackRock's scale justifies master-feeder complexity; smaller managers cannot
Figure (HELOCs) → Delaware Statutory Trust + Provenance
- Why: US assets, US borrowers, US investors, regulatory clarity
- Structure: DST holds loans → beneficial interests tokenized on Provenance
- Key innovation: Provenance blockchain provides UCC Article 8 "control" perfection on-chain
Securitize (Hamilton Lane, KKR) → Series LLC
- Why: Platform model — onboard many funds fast, single admin
- Structure: One Series LLC → each fund = one series
- Key insight: Operational velocity > bankruptcy certainty for their use case (fund interests, not direct asset ownership)
WisdomTree Prime → Delaware Statutory Trust
- Why: US retail-focused (Reg A+), money market fund, existing trust infrastructure
- Structure: DST holds Treasuries/repo → tokens = beneficial interests
- Key insight: Leverages existing mutual fund trust ops; not a "crypto-native" structure
Vietnam & Southeast Asia: The Missing Layer
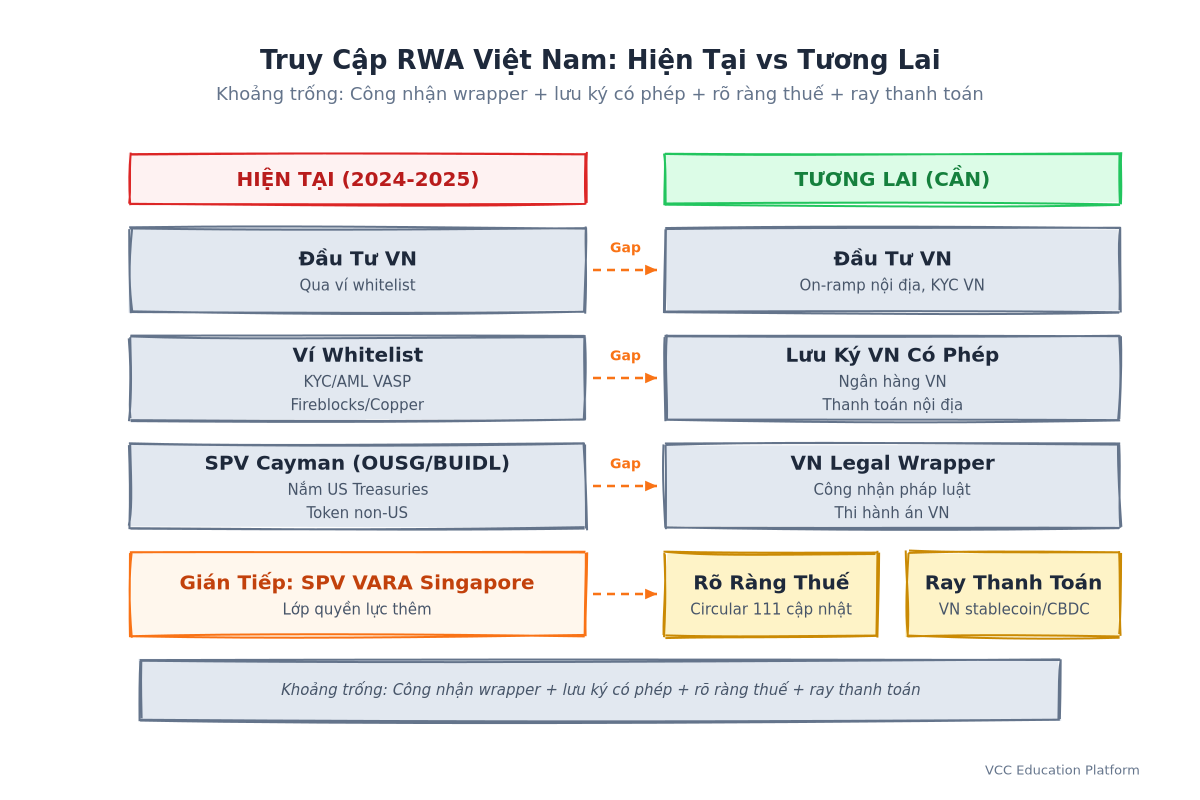
Current Reality (2024-2025)
- No domestic legal wrapper for tokenized RWA under Decree 13/2023
- VN investors access via Cayman SPVs (OUSG, BUIDL, USYC) through whitelisted wallets
- Tax treatment: Circular 111/2013/TT-BTC — offshore investment income taxable; reporting required
- Custody: No VN-licensed digital asset custodian → must use Fireblocks/Copper/Coinbase Prime
The Singapore Workaround
- VARA-licensed SPV (Dubai) or MAS-licensed (Singapore) issues tokens
- VN investors access via whitelisted wallets (KYC/AML by VASP)
- Not ideal: Adds jurisdictional layer; no VN legal recourse
What's Needed
- VN legal wrapper recognition — SPV/Trust law amendment for tokenized assets
- Licensed custodian — VN bank/broker with digital asset license
- Tax clarity — Circular update for tokenized fund distributions
- Settlement rail — VN domestic stablecoin or CBDC bridge for fiat on/off-ramp
Decision Checklist: 10 Questions Before You Sign
- Who are your investors? (US accredited / Non-US inst. / EU retail / APAC)
- What asset class? (Treasuries / Private credit / Real estate / Equities / Commodities)
- Single asset or multi-asset? (Need segregation? → SPC / Series LLC / SICAV)
- Regulatory target? (Reg D / Reg S / UCITS / AIFMD / VASP)
- Bankruptcy remoteness priority? (Highest → DST / Cayman SPC; Accept risk → Series LLC)
- Tax sensitivity? (US investors → avoid PFIC/ECI; Non-US → Cayman/BVI neutrality)
- Speed to market? (Fastest → BVI / Series LLC; Slowest → Lux SICAV)
- Budget? (Bootstrap → Series LLC / BVI; Institutional → Cayman / Lux)
- Admin ecosystem? (Existing relationships → Cayman / Delaware / Lux)
- Future expansion? (Plan master-feeder from Day 1 if multi-jurisdiction likely)
FAQ
Q: Can I just use a Wyoming LLC or Marshall Islands DAO LLC?
A: For production RWA with institutional investors — no. No bankruptcy remoteness precedent, no investor familiarity, regulatory uncertainty. Fine for experimentation; not for capital markets.Q: Is a Cayman SPV "tax evasion"?
A: No. Tax neutrality ≠ evasion. Cayman entities pay zero corporate tax. Investors pay tax in their jurisdiction on distributions/gains. This is standard international fund structuring (same as hedge funds, PE funds for 50+ years).Q: What happens if the SPV administrator goes rogue?
A: Independent directors + trustee + custodian create three independent gates. Administrator executes; directors approve; trustee oversees; custodian holds assets. All three must fail simultaneously.Q: Can I move from Series LLC to Cayman SPV later?
A: Yes — "redomiciliation" or asset transfer to new SPV. But triggers tax events, legal opinions, investor consent. Choose right the first time.Q: Does the token need to be a security?
A: For RWA with yield/ownership rights — almost certainly yes (Howey test: investment of money, common enterprise, expectation of profit from efforts of others). Structure accordingly (Reg D, Reg S, prospectus).Q: What about onshore US LLC for tokenized real estate?
A: Used for single-property, small-scale (e.g., RealT model). No bankruptcy remoteness vs sponsor. Fine for fractional ownership; not for institutional capital markets.Key Takeaways
- Legal wrapper = 4-layer stack (Entity, Bankruptcy Remoteness, Regulatory, Tax). All four must work.
- Investor geography decides structure — not asset type, not preference, not cost.
- Cayman SPV = global institutional standard. Delaware Statutory Trust = US gold standard for bankruptcy remoteness. Series LLC = platform efficiency (with untested bankruptcy risk). Lux SICAV = EU retail passport. BVI = APAC speed.
- Bankruptcy remoteness is theoretical until tested — no court has ruled on token holder rights in failed RWA SPV. True sale opinions are predictions.
- Master-feeder solves multi-jurisdiction but adds cost/complexity. Only justified at scale.
- Vietnam/SEA: No domestic wrapper yet. Singapore VARA SPV is current bridge. Watch Decree 13/2023 amendments.
Visual Markers Summary
SEO Keywords Integrated
- Primary: legal wrapper (H1, first 100 words, throughout)
- Secondary: Cayman SPV, Delaware Statutory Trust, BVI, Luxembourg SICAV, Series LLC (woven into H2s, body, FAQ)
- Semantic: bankruptcy remote, bankruptcy remoteness, SPV setup cost, tax, investor familiarity, true sale, ring-fencing, master-feeder, Reg D, Reg S, UCITS, VASP